What Is Blockchain Technology and How Does It Actually Work?
Author: Malik Mohsin Saleem Khan
Introduction: Understanding the Technology Behind Cryptocurrency
Blockchain technology has become one of the most discussed technologies in finance, technology, business, and digital assets.
The word blockchain is often associated with Bitcoin and cryptocurrency, but the technology itself is much broader than digital currencies. Blockchain can be used to create shared digital records, coordinate transactions between participants, track assets, support programmable applications, and establish records that are difficult to alter after they have been accepted by a network.
At its simplest level, a blockchain is a distributed digital ledger.
Instead of keeping information in one central database controlled by a single organization, blockchain systems can distribute copies of a ledger across multiple computers, often called nodes. Transactions or other records are grouped into blocks, and blocks are cryptographically connected to one another. NIST describes blockchain as a distributed, tamper-evident and tamper-resistant digital ledger in which records are grouped into blocks and linked using cryptographic mechanisms.
But how does this actually work?
How can thousands of computers agree on the same information?
How does a blockchain prevent someone from simply changing an old transaction?
What exactly is inside a block?
What is a cryptographic hash?
Why are digital signatures important?
And how do systems such as Bitcoin use proof of work while other blockchains use proof of stake?
To understand blockchain, it helps to break the technology into its individual components and then connect those components together.
This comprehensive guide explains what blockchain technology is, how blockchain works step by step, how transactions are verified, how blocks are created, how consensus works, why blockchain is considered difficult to tamper with, what smart contracts do, and where blockchain technology can be used beyond cryptocurrency.
What Is Blockchain Technology?
Blockchain technology is a method of maintaining a shared digital record across a distributed network.
A blockchain generally combines several technologies and concepts, including:
Distributed networking
Cryptographic hashing
Digital signatures
Public-key cryptography
Digital ledgers
Blocks
Consensus mechanisms
Peer-to-peer communication
Network validation
NIST explains that blockchain systems combine established computer-science mechanisms such as cryptographic hashes and digital signatures with distributed record-keeping concepts such as append-only ledgers.
The name blockchain comes from the way records are organized.
Transactions or other records are grouped into blocks.
Each block contains information that connects it to the previous block.
The result resembles a chain:
Block 1 → Block 2 → Block 3 → Block 4 → Block 5
If information inside an earlier block is changed, its cryptographic relationship with subsequent blocks changes as well.
This makes unauthorized modifications detectable and, depending on the specific blockchain’s consensus and security model, potentially extremely difficult to carry out successfully.
Blockchain Explained in Simple Terms
Imagine that ten people maintain identical copies of a shared notebook.
Every time someone wants to add a transaction, the network checks whether it follows the agreed rules.
Once the transaction is accepted, it is recorded in the next page.
Each page contains information that connects it to the previous page.
If someone secretly changes an old page, the other copies of the notebook will disagree, and the cryptographic connections will reveal that something has changed.
A real blockchain is much more sophisticated than this example, but the analogy demonstrates the fundamental concept:
Many participants maintain a shared record according to common rules rather than relying entirely on one central database.
The actual mechanisms vary considerably between blockchain networks.
How Does Blockchain Work?
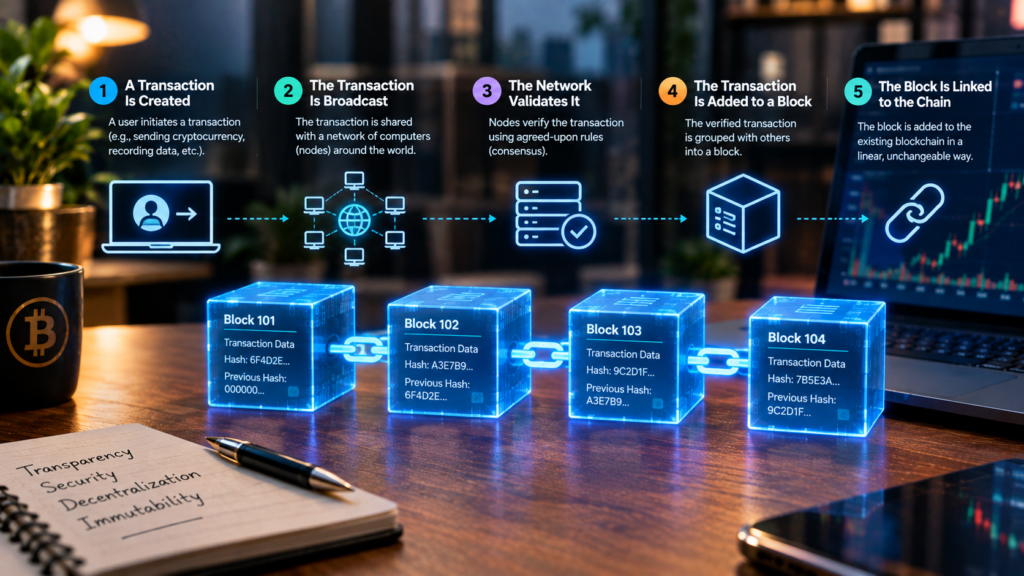
A simplified blockchain process can be described in the following sequence:
A user creates a transaction.
The transaction is digitally signed.
The transaction is broadcast to the network.
Network participants receive the transaction.
Nodes verify whether the transaction follows the blockchain’s rules.
Valid transactions are collected into a block.
A consensus mechanism determines how the block is accepted.
The accepted block is added to the blockchain.
Network participants update their copies of the ledger.
Later blocks build on top of the previous block.
The exact process depends on the blockchain.
Bitcoin, Ethereum, and permissioned enterprise blockchains do not all operate in exactly the same way.
Nevertheless, these steps provide a useful conceptual framework.
The Main Components of a Blockchain
To understand blockchain technology properly, it is useful to understand its major components.
1. Transactions
Transactions represent changes or instructions recorded by the blockchain.
For a cryptocurrency such as Bitcoin, a transaction may represent the transfer of digital value.
For other blockchains, a transaction might:
Transfer tokens
Call a smart contract
Change application data
Register an asset
Execute a program
Update a digital record
2. Blocks
A block is a collection of records accepted by the blockchain network.
A typical block may contain:
Transaction data
A timestamp or block-related metadata
A reference to the previous block
A cryptographic hash
Consensus-related information
Other protocol-specific data
Blocks are the containers that organize blockchain records.
3. Hashes
A cryptographic hash function takes input data and produces a fixed-size output called a hash or digest.
For example:
Input → Cryptographic hash function → Hash
Even a small change to the input can produce a dramatically different output.
NIST explains that hashing allows participants to independently calculate a digest from data and compare the result to detect whether the underlying data has changed.
This makes hashing fundamental to blockchain integrity.
4. Nodes
A node is a computer participating in a blockchain network.
Different blockchain networks can have different types of nodes.
Depending on the protocol, nodes may:
Store blockchain data
Validate transactions
Relay transactions
Validate blocks
Participate in consensus
Maintain network connectivity
Instead of depending on one server, blockchain networks can distribute responsibility among many participating computers.
5. Consensus
Consensus is the process through which network participants agree on which transactions and blocks should become part of the accepted blockchain history.
Different blockchain networks use different consensus mechanisms.
Examples include:
Proof of Work
Proof of Stake
Proof of Authority
Other specialized consensus models
NIST identifies consensus mechanisms as a core part of blockchain architecture and discusses several different approaches.
What Is a Blockchain Block?
A block can be thought of as a container for a group of transactions or records.
A simplified block might look like this:
Block #1050
Transaction A
Transaction B
Transaction C
Transaction D
Previous block hash
Current block information
Consensus data
The block references the previous block.
The next block references Block #1050.
This creates the chain.
Block 1049 → Block 1050 → Block 1051 → Block 1052
The important concept is that blocks are not independent database pages.
They are cryptographically connected.
How Cryptographic Hashing Works
Hashing is one of the foundations of blockchain technology.
Imagine a file containing the following text:
Hello Blockchain
A cryptographic hash function converts that data into a hash.
If you change the input to:
Hello Blockchain!
the resulting hash will be different.
The hash does not work like a normal encryption system where you simply decrypt the result to retrieve the original text.
Instead, a cryptographic hash is primarily used to create a compact representation of data that can be checked for integrity.
Why Is Hashing Important?
Hashing helps blockchain networks:
Detect changes
Link blocks
Identify data
Verify integrity
Support consensus mechanisms
Secure certain blockchain operations
NIST identifies cryptographic hash functions as a fundamental component of blockchain systems.
What Does “Tamper-Resistant” Mean?
Blockchain is sometimes described as immutable, but it is more accurate to understand the technology as providing strong tamper evidence and, depending on the network, substantial resistance to unauthorized modification.
NIST uses the concepts tamper-evident and tamper-resistant to describe blockchain systems.
Suppose someone changes information in an old block.
That change alters the block’s hash.
Because subsequent blocks contain cryptographic references to earlier blocks, the alteration can affect the chain of references.
The attacker would therefore need to overcome not only the altered block but also the subsequent blockchain history and the network’s consensus rules.
The exact difficulty depends on the blockchain’s architecture.
What Is a Distributed Ledger?
A distributed ledger is a shared record that is maintained across multiple participants rather than being stored exclusively in one central location.
Traditional systems often use a centralized database.
For example:
User → Bank → Central Database
The bank maintains the official record.
A blockchain can instead use a distributed model:
User ↔ Network Nodes ↔ Shared Ledger
Different nodes maintain copies or relevant portions of the blockchain according to the network’s design.
NIST defines blockchain as a distributed digital ledger that generally operates without a central repository and often without a central authority.
Blockchain vs. Traditional Database
Blockchain is not automatically better than a traditional database.
The technologies solve different problems.
| Feature | Traditional Database | Blockchain |
|---|---|---|
| Central administrator | Usually present | May be absent or distributed |
| Data structure | Flexible | Protocol-defined |
| Control | Often centralized | Often distributed |
| Modification | Administrator can usually edit data | Historical changes may be highly constrained |
| Consensus | Usually unnecessary among database users | Core feature of many blockchains |
| Performance | Often very high | Depends on blockchain design |
| Transparency | Depends on system | Can be public or permissioned |
| Cryptography | Used where appropriate | Fundamental to many blockchain functions |
For a simple company’s internal customer database, blockchain may provide unnecessary complexity.
But where multiple organizations need to coordinate records without relying on one party to maintain the definitive database, a blockchain may have useful characteristics.
How a Blockchain Transaction Works
Let’s examine a cryptocurrency transaction step by step.
Imagine Alice wants to send digital currency to Bob.
Step 1: Alice Creates a Transaction
Alice’s wallet prepares a transaction specifying the relevant information, such as:
The amount
The destination
Transaction-related inputs or references
Appropriate network data
Step 2: Alice Signs the Transaction
Alice’s wallet uses cryptographic keys to produce a digital signature.
The signature helps demonstrate that the transaction was authorized by the holder of the relevant private key.
This is where public-key cryptography becomes important.
Public Keys and Private Keys
Blockchain wallets typically use cryptographic key pairs.
They consist broadly of:
A private key
A public key
The private key is secret.
The public key can be shared according to the protocol’s design.
The private key is used to authorize certain actions, while the corresponding public information allows others to verify the signature.
NIST identifies asymmetric-key cryptography and digital signatures as core blockchain components.
Why the Private Key Matters
A private key can effectively function as control over blockchain assets or permissions associated with that key.
If a user loses the private key or exposes it to an attacker, recovering control may be extremely difficult or impossible depending on the system.
This is why wallet security is one of the most important aspects of using blockchain-based assets.
Step 3: The Transaction Is Broadcast
After Alice’s transaction is signed, it is sent to the blockchain network.
Other participating nodes receive the transaction.
The transaction does not immediately become a permanent part of the blockchain.
First, it needs to be checked.
Step 4: Nodes Validate the Transaction
Network participants can verify whether the transaction follows the blockchain’s rules.
Depending on the blockchain, validation may include checking:
Digital signatures
Available funds or valid transaction inputs
Transaction format
Protocol rules
Whether the transaction attempts to spend something improperly
Smart-contract conditions
Invalid transactions are rejected.
Valid transactions can continue through the process.
Step 5: Valid Transactions Enter the Pool
Many blockchain networks maintain a temporary collection of transactions waiting to be included in a block.
For Bitcoin, this is commonly called the mempool.
Think of it as a waiting area.
The transaction has been broadcast and recognized by the network, but it has not necessarily been permanently recorded in a confirmed block yet.
Step 6: Transactions Are Grouped Into a Block
A block producer collects valid transactions into a candidate block.
The exact process depends on the consensus mechanism.
In Bitcoin, miners compete to produce blocks using proof of work.
In proof-of-stake systems, validators participate according to the network’s staking and consensus rules.
Step 7: Consensus Determines Acceptance
This is one of the most important parts of blockchain technology.
Multiple computers may receive transactions at slightly different times.
How does the network determine which transactions become part of the accepted history?
The answer is consensus.
A consensus mechanism provides rules for deciding which blocks are valid and how participants should agree on the blockchain’s state.
What Is Proof of Work?
Proof of Work, commonly abbreviated as PoW, is the consensus mechanism used by Bitcoin.
Bitcoin’s original design combines a peer-to-peer network with cryptographic hashing and proof of work to establish an ordered transaction history without relying on a central authority.
In simplified terms, miners compete to find a valid solution to a computational puzzle.
They repeatedly modify a value called a nonce and calculate hashes.
They are looking for a hash that satisfies the network’s difficulty requirements.
When a miner finds a valid solution, it broadcasts the proposed block.
Other nodes can verify the proof much more quickly than it took to discover.
Why Does Proof of Work Matter?
Proof of work makes producing valid blocks computationally expensive.
It also means that changing historical blocks can require substantial additional computation.
Bitcoin’s developer documentation explains that chaining blocks together means modifying a transaction in an earlier block requires modifying subsequent blocks as well, increasing the work required as more blocks are added.
This is one of the mechanisms that contributes to Bitcoin’s security model.
What Is Proof of Stake?
Proof of Stake, or PoS, is another major consensus approach.
Instead of requiring miners to perform computational work, proof-of-stake systems use validators who commit or stake assets according to the network’s rules.
Validators may be selected to propose or attest to blocks.
Ethereum is a major example of a proof-of-stake blockchain.
Proof of stake can provide a different security and incentive structure from proof of work.
Proof of Work vs. Proof of Stake
| Feature | Proof of Work | Proof of Stake |
|---|---|---|
| Main participants | Miners | Validators |
| Resource used | Computing power and energy | Staked assets |
| Block participation | Computational competition | Protocol-defined validator selection |
| Example | Bitcoin | Ethereum |
| Security mechanism | Economic cost of computation | Economic value at stake |
Neither label alone tells you everything about a blockchain’s security.
The details of the protocol matter.
Step 8: The Block Is Added to the Blockchain
Once a block is accepted according to the network’s consensus rules, it becomes part of the blockchain.
The chain now looks something like:
Block 100 → Block 101 → Block 102 → Block 103
Each new block builds on previous blockchain history.
The transaction is now recorded within that history.
Step 9: More Blocks Increase Confirmation
In blockchain systems such as Bitcoin, additional blocks after a transaction provide additional confirmation.
Suppose your transaction is included in Block 900.
The chain later adds:
Block 901
Block 902
Block 903
Your transaction now has additional blocks built on top of it.
This generally makes a successful reversal increasingly difficult under the network’s consensus assumptions.
The exact meaning of “confirmation” and finality differs among blockchain protocols.
What Is Blockchain Finality?
Finality refers to the point at which a blockchain transaction is considered irreversible or extremely difficult to reverse according to its protocol.
Different blockchain systems achieve finality differently.
Some use probabilistic finality.
Others use explicit or deterministic finality mechanisms.
Bitcoin’s model is commonly described in terms of increasing confidence as additional blocks are added.
Proof-of-stake systems can use different mechanisms to establish finality.
This is another reason why it is important not to assume that every blockchain works exactly like Bitcoin.
Why Is Blockchain Difficult to Hack?
The answer is not simply “because blockchain is encrypted.”
Blockchain security comes from multiple mechanisms working together.
These can include:
Cryptographic hashing
Digital signatures
Private keys
Distributed nodes
Consensus mechanisms
Economic incentives
Validation rules
Network architecture
NIST emphasizes that blockchain’s security characteristics arise from combinations of cryptographic mechanisms, distributed architecture, and consensus processes.
Is Blockchain Completely Unhackable?
No.
This is an important distinction.
Blockchain technology is not magically immune to attacks.
Possible risks can include:
Private-key theft
Smart-contract vulnerabilities
Exchange compromises
Bridge exploits
Malicious applications
Consensus attacks
Governance attacks
Implementation bugs
Social engineering
The blockchain itself can be highly resistant to unauthorized modification while applications built around it can still contain vulnerabilities.
This distinction is essential.
Blockchain Security vs. Wallet Security
Suppose the Bitcoin blockchain is functioning correctly.
That does not mean a user’s computer or wallet is automatically secure.
If an attacker obtains a user’s private key, the attacker may be able to authorize transactions.
Therefore:
Blockchain security ≠ personal wallet security
Both matter.
What Is a Smart Contract?
A smart contract is a program deployed on a blockchain that can execute according to predefined rules.
Instead of requiring a human intermediary to manually enforce every condition, the blockchain can execute the programmed instructions when the required conditions are satisfied.
Smart contracts are particularly important on programmable blockchains.
They can be used for:
Decentralized exchanges
Lending applications
Token creation
NFTs
Games
Automated payments
Governance systems
Financial applications
NIST includes smart contracts among important blockchain concepts and technologies.
How Smart Contracts Work
Consider a simplified example.
A smart contract might contain a rule:
If Alice sends 1 token → transfer 10 digital units to Alice.
The blockchain verifies the transaction.
The smart contract executes according to its programmed conditions.
The result is recorded according to the blockchain’s rules.
This creates programmable behavior directly within a blockchain environment.
Blockchain Oracles
Smart contracts can operate on information available within their blockchain environment.
But what happens if a smart contract needs external information?
For example:
What is the current exchange rate of an asset?
A blockchain cannot automatically trust every external website.
This is where oracles can be used.
An oracle can provide external information to a blockchain application according to the design of the oracle system.
NIST’s blockchain overview identifies data oracles as an important blockchain concept.
Public vs. Private Blockchains
Not every blockchain is open to everyone.
There are different blockchain permission models.
Public Blockchain
A public blockchain generally allows broad participation.
Examples include:
Bitcoin
Ethereum
Participants can interact with the network according to its rules.
Permissioned Blockchain
A permissioned blockchain restricts certain activities to authorized participants.
These systems may be used by:
Companies
Financial institutions
Government organizations
Industry groups
Permissioned networks can provide greater control over participation.
Permissionless vs. Permissioned Networks
The distinction can be summarized as follows:
| Feature | Permissionless | Permissioned |
|---|---|---|
| Participation | Broad/open | Restricted |
| Identity requirements | Often limited | Usually stronger |
| Governance | Distributed protocol rules | Controlled by organizations or consortium |
| Common use | Public cryptocurrency networks | Enterprise systems |
| Transparency | Often high | Can be restricted |
There is no universal blockchain design that is appropriate for every situation.
Why Blockchain Does Not Need a Central Authority
Traditional digital systems often rely on a trusted central party.
For example:
Bank → maintains account balances
Blockchain systems can instead distribute record maintenance among network participants.
The network rules determine:
What constitutes a valid transaction
Which blocks are valid
How participants reach consensus
How conflicts are resolved
This allows participants who may not fully trust one another to coordinate around a shared ledger.
NIST describes blockchain as a mechanism that can allow communities to maintain shared records without necessarily relying on a central repository or central authority.
What Problem Does Blockchain Solve?
One of blockchain’s most important concepts is the coordination problem.
Imagine several companies need to maintain a shared record.
Company A has one database.
Company B has another.
Company C has another.
They must constantly reconcile their records.
A shared blockchain ledger can provide a common record that participants update according to shared rules.
This can potentially reduce the need for multiple organizations to maintain separate versions of the same record.
Blockchain and the Double-Spending Problem
Digital information can normally be copied.
If you send someone a photo, you still have a copy.
But digital money requires a way to prevent someone from spending the same unit twice.
Bitcoin’s original design specifically addressed the double-spending problem using a peer-to-peer network, digital signatures, transaction history, and proof of work.
The blockchain provides an agreed transaction history that allows the network to determine which transactions are valid.
This was a major development in digital money.
Blockchain and Cryptocurrency
Cryptocurrency is one of the most famous applications of blockchain technology.
Bitcoin demonstrated how a decentralized network could maintain a shared transaction ledger without depending on a conventional financial intermediary.
Other blockchain networks expanded the concept.
Some support:
Smart contracts
DeFi
NFTs
Stablecoins
Tokenized assets
Decentralized applications
Gaming
Digital identity
However, blockchain technology does not require cryptocurrency in every implementation.
Blockchain Applications Beyond Cryptocurrency
Blockchain can potentially be used for many types of records and coordination.
NIST identifies areas including supply chains, data registries, digital identification, and records management as potential blockchain applications.
Other potential applications include:
Supply Chain Management
Blockchain can record events associated with products as they move through a supply chain.
Digital Identity
Blockchain-based systems can potentially help manage certain forms of digital identity information.
Asset Tracking
Organizations can record ownership or movement of assets.
Document Verification
Blockchain systems can help establish evidence that a particular digital record existed at a particular time.
Healthcare
Blockchain has been explored for certain types of data coordination and record management.
Financial Settlement
Blockchain can support certain forms of digital asset transfer and settlement.
Blockchain in Supply Chains
Consider a product traveling through several stages:
Manufacturer → Distributor → Warehouse → Retailer → Customer
Each participant could potentially record relevant events.
A blockchain-based system could create a shared history of:
Production
Shipment
Receipt
Transfer
Verification
The technology does not automatically prove that every physical-world statement is true.
If someone enters false information, the blockchain can preserve the false information.
This is a crucial limitation.
Blockchain can protect the integrity of recorded data without guaranteeing the truthfulness of the original input.
Blockchain and Digital Ownership
Blockchain networks can also represent digital ownership through tokens.
NIST describes blockchain technology as enabling a software paradigm for managing digital ownership using tokens, public-key cryptography, peer-to-peer interaction, and distributed ledgers.
Tokens can represent different things depending on the system.
They can be used to represent:
Digital currencies
Utility rights
Governance rights
Collectibles
Financial assets
Access rights
Other forms of digital representation
The legal meaning of a token depends on the specific system and applicable laws.
What Makes Blockchain Different From Cloud Storage?
Cloud storage and blockchain solve different problems.
Cloud storage is primarily designed to store and retrieve data efficiently.
Blockchain is primarily designed around shared state, verification, integrity, and agreement among network participants.
A blockchain is therefore not simply:
“A decentralized cloud drive.”
Putting large files directly onto a blockchain may be inefficient or impractical.
Blockchain is generally more useful when the key problem involves:
Shared records
Ownership
Verification
Coordination
Consensus
Trust minimization
The Limitations of Blockchain Technology
Blockchain has important advantages, but it is not a perfect solution.
1. Scalability
Some blockchains struggle to process enormous transaction volumes while maintaining their desired levels of decentralization and security.
2. Complexity
Blockchain systems can be technically difficult to design and operate.
3. User Experience
Wallets, private keys, transaction fees, and network selection can be confusing for beginners.
4. Energy Consumption
Certain consensus mechanisms, especially proof of work, require substantial computational resources.
5. Irreversible Transactions
If a transaction is incorrectly sent or a private key is compromised, recovery may be difficult.
6. Smart-Contract Bugs
A blockchain application can contain software vulnerabilities.
7. Regulatory Uncertainty
Blockchain applications may face different regulatory requirements across jurisdictions.
8. Data Quality
Blockchain does not automatically verify whether information entered into the system is truthful.
NIST emphasizes that blockchain is not a universal solution and that implementations involve limitations and design considerations.
The Blockchain Trilemma
Blockchain designers often discuss a trade-off between:
Decentralization
Security
Scalability
The basic idea is that optimizing one characteristic can create challenges for the others.
For example:
Increasing transaction capacity may affect decentralization.
Increasing decentralization may make coordination more difficult.
Increasing complexity may introduce additional security considerations.
Different blockchain projects make different design choices.
Why Blockchain Is Considered Trust-Minimized
Blockchain does not eliminate trust completely.
Instead, it can change where trust is placed.
Traditional systems may require users to trust:
A bank
A company
A government database
A centralized platform
A blockchain can shift some of that reliance toward:
Cryptographic proofs
Protocol rules
Distributed validation
Consensus mechanisms
Open verification
Therefore, “trustless” is often better understood as trust-minimized rather than meaning that absolutely no trust exists.
Users still need to trust software, hardware, wallets, developers, economic incentives, and sometimes external data sources.
A Complete Example: Sending Bitcoin
Let’s bring everything together.
Suppose Alice wants to send Bitcoin to Bob.
Step 1
Alice opens her wallet.
Step 2
She enters Bob’s destination information and the amount.
Step 3
Her wallet creates a transaction.
Step 4
The transaction is signed using Alice’s private key.
Step 5
The transaction is broadcast to Bitcoin’s peer-to-peer network.
Step 6
Nodes validate the transaction.
Step 7
The transaction waits to be included in a block.
Step 8
A miner selects valid transactions and creates a candidate block.
Step 9
The miner performs proof-of-work computations.
Step 10
A valid block is broadcast.
Step 11
Other nodes verify the block.
Step 12
The accepted block becomes part of the blockchain.
Step 13
Additional blocks are added afterward.
Step 14
Confidence that the transaction will remain in the accepted history increases as the chain grows.
This sequence demonstrates how cryptography, networking, validation, mining, consensus, and distributed record-keeping work together.
Why Every Blockchain Is Not the Same
One of the biggest misconceptions about blockchain is treating all blockchain networks as identical.
They are not.
Bitcoin and Ethereum differ.
Ethereum and Solana differ.
Public blockchains differ from permissioned enterprise networks.
Proof-of-work systems differ from proof-of-stake systems.
Some blockchains prioritize:
Security
Decentralization
Speed
Privacy
Smart contracts
Interoperability
Enterprise control
The term blockchain describes a broad technological category rather than one single implementation.
How to Evaluate a Blockchain Project
If you are researching a blockchain network, consider the following questions:
Technology
How does the blockchain work?
What consensus mechanism does it use?
How are transactions validated?
Security
How is the network protected?
What are its major attack assumptions?
Decentralization
Who operates the network?
How distributed are validators or nodes?
Economics
How are participants rewarded?
What is the token supply model?
Adoption
Are people actually using the network?
What applications exist?
Development
Is the software actively maintained?
Is there a strong developer community?
Governance
Who can change the protocol?
How are upgrades approved?
Scalability
How does the network handle increased demand?
A serious blockchain analysis should look beyond marketing claims.
Frequently Asked Questions About Blockchain Technology
What is blockchain in simple words?
Blockchain is a shared digital ledger maintained by a network of participants. Records are grouped into blocks and cryptographically linked together, making unauthorized historical changes detectable and often difficult to accomplish.
How does blockchain work?
A blockchain generally receives transactions, validates them according to protocol rules, groups valid records into blocks, reaches consensus on those blocks, and adds accepted blocks to a growing chain.
Is blockchain the same as Bitcoin?
No.
Bitcoin is a cryptocurrency and blockchain network.
Blockchain is the broader technology underlying Bitcoin and many other systems.
Is blockchain decentralized?
Many public blockchains are designed to be decentralized, but decentralization varies significantly between networks.
Some blockchain systems are permissioned and controlled by a defined group of organizations.
What is a blockchain node?
A node is a computer participating in a blockchain network. Depending on the protocol, nodes can store data, validate transactions, relay information, or participate in consensus.
What is a blockchain block?
A block is a collection of blockchain records bundled together according to the network’s rules. Blocks are connected to earlier blocks through cryptographic references.
What is hashing in blockchain?
Hashing is the process of using a cryptographic hash function to convert data into a fixed-size digest. Changes to the input generally produce a different digest, making hashes useful for data integrity and blockchain linking.
What is proof of work?
Proof of work is a consensus mechanism in which participants perform computational work to create valid blocks. Bitcoin uses proof of work.
What is proof of stake?
Proof of stake is a consensus approach in which participants called validators commit or stake assets and participate in network consensus according to protocol rules.
What is a smart contract?
A smart contract is a blockchain-based program that executes according to predefined conditions.
Can blockchain data be changed?
Blockchain data can be subject to protocol-specific mechanisms such as forks, reorganizations, administrative controls in permissioned systems, or other exceptions. However, public blockchains are generally designed to make unauthorized historical modification difficult. NIST therefore emphasizes tamper evidence and tamper resistance rather than treating every blockchain as absolutely immutable.
Is blockchain secure?
Blockchain systems can provide strong security properties through cryptography, distributed architecture, and consensus, but no technology is completely risk-free. Wallets, smart contracts, exchanges, bridges, and other components can still be attacked.
Does blockchain require cryptocurrency?
No.
Cryptocurrency is one important application of blockchain, but blockchain systems can also be designed for enterprise records, supply chains, identity, asset tracking, and other purposes.
Conclusion: Understanding How Blockchain Really Works
Blockchain technology can initially seem complicated because it combines several areas of computer science into one system.
However, the fundamental concept is easier to understand when broken down.
A blockchain is essentially a shared digital ledger maintained according to cryptographic and consensus rules.
Transactions or other records are grouped into blocks.
Blocks are connected using cryptographic references.
Network participants validate transactions and blocks.
Consensus mechanisms determine which blocks become part of the accepted history.
Cryptographic signatures help prove authorization.
Hashing helps protect data integrity.
Distributed nodes help maintain copies or representations of the ledger.
Together, these mechanisms create a system capable of maintaining shared digital records without necessarily depending on one central database administrator.
Bitcoin demonstrated one powerful application of this architecture by combining a peer-to-peer network, digital signatures, hashing, proof of work, and a blockchain to address the double-spending problem.
But blockchain technology has developed far beyond Bitcoin.
Modern blockchain networks can support smart contracts, decentralized applications, digital tokens, financial systems, identity systems, asset tracking, and other forms of digital coordination.
At the same time, blockchain is not a universal replacement for databases or centralized systems.
Its advantages become most relevant when organizations or individuals need shared records, verifiability, distributed control, programmable assets, or coordination among parties that may not want to rely entirely on a single intermediary.
The most important thing to understand is that blockchain is not magic.
Its security and usefulness come from carefully designed combinations of cryptography, networking, incentives, data structures, validation, and consensus.
Once those individual components are understood, the idea behind blockchain becomes much clearer.
It is not simply a chain of digital blocks.
It is a complete system for helping multiple participants maintain a shared view of digital information according to rules that can be independently verified.
That is the foundation on which cryptocurrencies and many other blockchain applications are being built.
Leave a Reply